

Financial advice for an inheritance:
What to do with inherited money in Australia
When you receive an inheritance, proper financial management is often far from your mind as you navigate the emotions of losing a loved one. That’s why professional financial advice is vital.
Reach out to our private wealth management team today and find out how you can use your inheritance to carry on your family’s legacy.

Download the inheritance planning guide
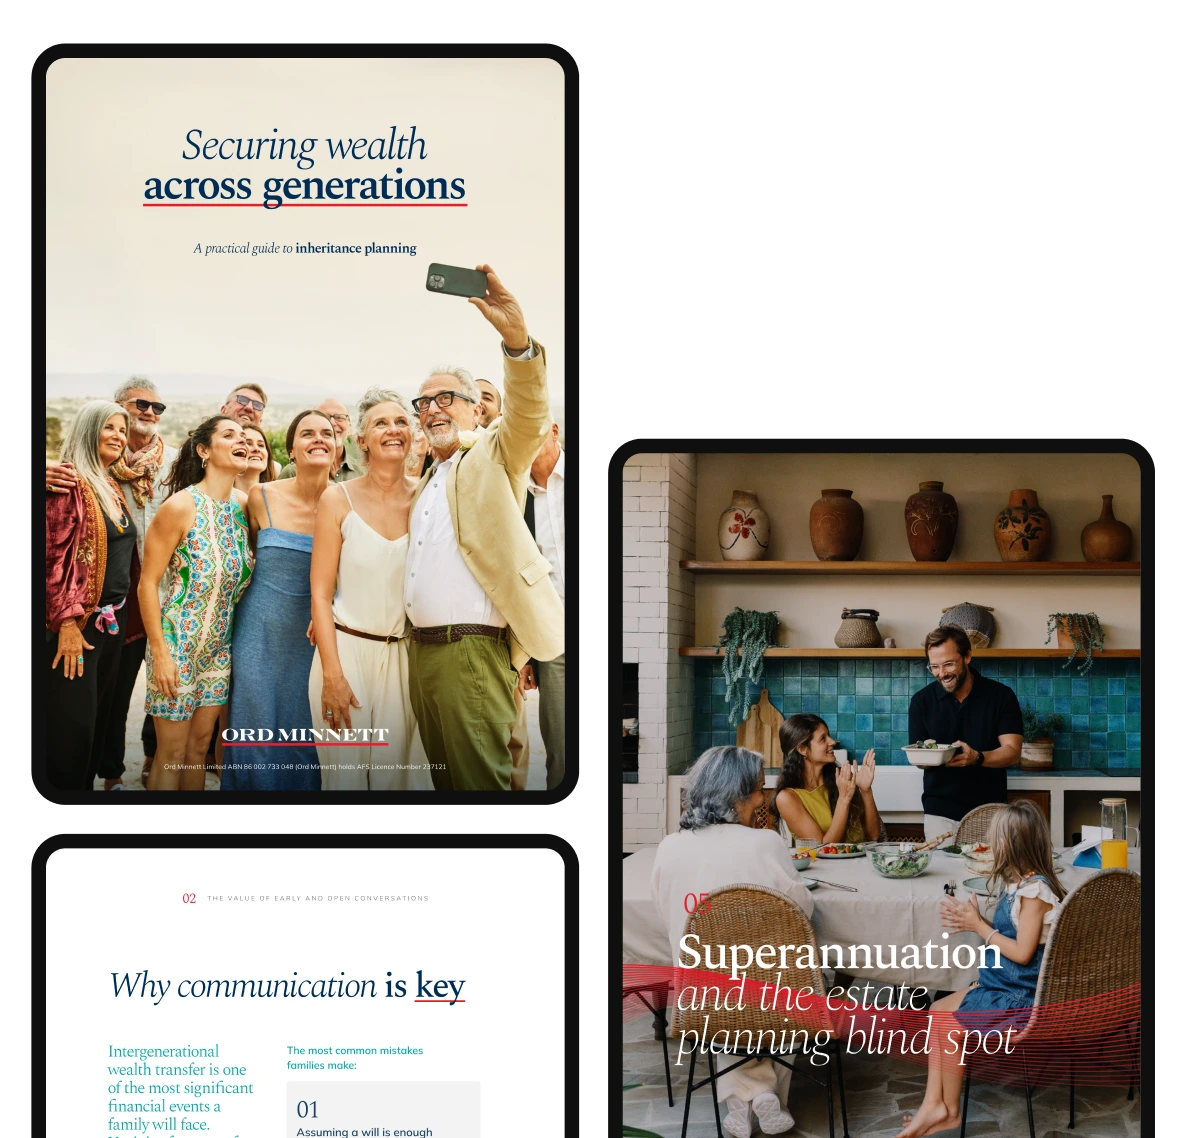
Unsure of your next move in leaving or receiving an inheritance? Download our comprehensive guide to inheritance planning.
We've broken down the key strategies to consider when you are leaving or receiving an inheritance. Get the information you need to implement an inheritance financial strategy with confidence.
We collect your personal information so we can contact you with marketing communications about our products and services. We may also use your information to improve our offerings. You can opt out of receiving marketing at any time by following the unsubscribe instructions in our communications. For more information, please see our Privacy Policy.

How to approach managingan inheritance: First steps
If you’ve just received an inheritance, here are a few key first steps:
Avoid rash financial decisions:
Don’t make any big moves with your new assets straight away. You have plenty of time to think about what to do with your inheritance before you begin executing any strategies.
Confirm the estate:
Inspect documents like the will, inventory of assets or liabilities, and statement of estate accounts. Work with a legal professional to understand exactly what you now own.
“Park” cash:
If you receive a large amount of cash, make sure that it is initially moved to a “safe” destination like a savings account.
Devising a strategy:
Now, you’re ready to develop a real strategy to move forward with. Get in touch with professional financial advisers like the team at Ord Minnett to find the right strategies to manage your windfall. Whether you want to reduce debts or work towards complete financial freedom, we're here to support your journey.
Professional financial advice for an inheritance
Receiving an inheritance is a beautiful opportunity to build on the legacy left by your loved one. With help from our private wealth management team, you can make informed decisions to help maximise your inheritance.
Start a conversation today and find out why we’re trusted with $73.6 billion* in Funds Under Advice.
How inherited assets affect strategy
The right approach to managing a windfall depends heavily on the assets you have inherited. Here’s how our private wealth management team can help you make the right decisions with your new assets:
Property
Inheriting property comes with both emotional and financial complexity. It’s crucial to make the right decisions with family homes and investment properties alike.
There are plenty of paths to take after inheriting property, including:
- Moving in.
- Buying out shares of co-inheritors.
- Quickly selling the property to distribute cash among co-inheritors.
- Holding the property as an asset.
Whichever route you take, our team of Private Wealth Advisers can advise you on optimal strategies. We work with legal and tax experts to help you understand tax obligations and opportunities for efficiencies, like the main residence exemption.
Shares
Inheriting an investment portfolio of listed equities, managed funds, or exchange-traded funds (ETFs) gives you an instant growth-oriented asset base. There’s generally no CGT liability until you sell or dispose of the shares, so you have all the time you need to incorporate them into your investment strategy.
A professional financial adviser from Ord Minnett can help analyse your current portfolio and examine how your new assets can best complement it. If you want to sell some shares, we’ll explore the best ways to do that without facing a massive tax bill in a single financial year.
Super
Managing a superannuation death benefit can be complex. Our team is experienced in advising clients in a broad range of scenarios. Whether you’ve received a lump sum or an income stream, we’ll ensure you understand your tax position, and the strategies to best manage the opportunities of inherited super.
We can also help manage inheritances to minors and the impacts of Division 296. Start a conversation with an expert adviser today to take an informed approach to handling superannuation death benefits.
Cash
Cash might appear to be the simplest form of inheritance, but managing inheritance money presents challenges. On average, around 70% of wealth is lost by the second generation of inheritors. Fortunately, working with professional financial advisers can help you make the right decisions with your inheritance.
Creating a co-ordinated, highly personalised strategy is essential for making the most of inherited cash. Our private wealth management team will help you balance options like debt reduction and investment to build a more prosperous life.
Family trusts and companies
Inheriting an interest in a family trust or company can feel complicated. During what’s already an extremely difficult time, a private wealth management team will help you understand your rights, obligations, and opportunities.
Our team can help you understand governance documents like trust deeds, shareholder agreements, and company constitutions. Speak with a private wealth adviser and determine your next steps.
Australia has no inheritance tax, but your inheritance is not tax-free
There is no inheritance tax in Australia, allowing you to actually end up with a large amount of what’s left to you. However, there are a number of taxes that can impact inheritances in various ways. These are crucial to understand when managing an intergenerational wealth transfer.
- 01
Capital Gains Tax
Capital Gains Tax (CGT) is a tax that applies to profits earned when an asset is sold or otherwise disposed of. If you inherit an asset like business shares or an investment property, and sell it, you will generally need to pay CGT on any profit you make.
CGT generally applies when a sale is completed, rather than the point of inheritance. When filing your tax return, any CGT profits are simply added to your income and taxed at the appropriate marginal rate.
For assets held for longer than 12 months, a 50% CGT discount applies. This timeframe includes the period the asset was held by the deceased.
A major exemption for CGT on inherited assets applies to properties that were the main residence of the deceased. If you sell this kind of property within two years of the deceased’s death, any profits may be exempt from CGT. Find out more here.
- 02
Superannuation taxes
For many Australians, super is their single most valuable asset, making it a critical part of millions of estates. When someone dies, their remaining super balance and any insurance benefits are generally paid to a nominated beneficiary.
Lump sums inherited by dependants under superannuation law are entirely tax-free. This generally excludes adult children, meaning for most inheritors, super death benefits are taxable. Dependants under superannuation law can inherit super death benefits as an income stream, while adult children generally cannot.
The tax on a superannuation death benefit is calculated using the proportioning rule. The taxable portion is generally taxed at a maximum rate of 17%. If elements of super haven’t already been taxed inside the fund, they will be taxed at a maximum rate of 32%. These percentages include the 2% Medicare levy, but the levy generally doesn’t apply if the benefit is paid via a deceased estate.
If a benefit is paid as an income stream, the taxed element is tax-free if either the deceased was 60 or over at death, or the recipient is 60 or over. If both were under 60, the taxed element is taxed at marginal rates, with a 15% tax offset until the recipient turns 60. Different rules apply to any untaxed element.
Due to Division 296, an additional 15% tax on realised super earnings applies for super balances over $3 million. This tax applies to earnings attributable to the balance above the threshold. In the year a member dies, any Division 296 tax owed must be paid by the deceased estate, unless they died on or before 30 June 2027.
- 03
Stamp duty
Stamp duty, also known as transfer duty, is a tax that applies when transferring the ownership of property or certain other assets. Stamp duty is applied at the state level, so it can work differently depending on where you live.
Inheriting residential or commercial property directly through a deceased estate generally doesn’t incur standard stamp duty. A small fixed or nominal duty may be required, with separate land title registration fees potentially applying.
If you inherit a property alongside other family members, and you buy out your relative’s shares in the property, standard stamp duty must generally be paid on the acquired shares. If you are gifted property while your family member is still alive, full stamp duty must generally be paid based on the property’s market value, even if you give nothing in return for it.
Stamp duty can work differently when you inherit or are gifted other assets, like business shares. If you’re unclear on how stamp duty might impact you, start a conversation with an Ord Minnett adviser to receive comprehensive guidance.
- 04
Trust taxation
Since family trusts are not owned entirely by an individual, they cannot be “inherited” in the same way as cash or property. They can be an effective option for passing on wealth.
If a loved one leaves assets behind in a family trust, taxation may impact you in various ways. If you receive ongoing income through the trust, it will be added to your income and taxed at the appropriate marginal rate.
Income distributed to minors is taxed at a penalty rate of 47% (including the Medicare levy) if the sum exceeds $1,307. Different rates apply to lower sums. Testamentary trusts can be set up through a will, allowing income originating from the deceased estate to be distributed to minors at adult rates, rather than minor penalty rates.
If a trustee transfers legal ownership of an asset to an individual beneficiary, this is considered a tax event. This means it will generally incur CGT and stamp duty, unless conditions for an exemption are met.
Should your inheritance go into superannuation?
Putting your inheritance into superannuation can be an effective strategy for many Australians. This strategy can have the following benefits.
However, placing inherited money into super might not be the right choice for everyone, for the following reasons:
Tax benefits:
Super is one of Australia’s most tax-effective forms of investment, with earnings on balances under $3 million taxed at a maximum of 15%.
Growth towards retirement:
Super aims to achieve capital growth in a highly regulated environment, bolstering your retirement savings. Supporting your super balance with an inheritance can be an effective way to achieve a more prosperous, enjoyable retirement.
Control:
Many super funds offer a range of investment options and strategies.
Access:
Once money has been placed in super, it cannot be accessed unless a condition of release is met. This must be carefully factored into your financial strategy.
Contribution caps:
There are annual caps on concessional and non-concessional super contributions. Exceeding these caps can mean paying extra tax, which can reduce the incentive to contribute to your super.
Division 296:
If your Total Superannuation Balance (TSB) exceeds $3 million, you’ll have to pay an additional 15% tax on realised superannuation earnings attributable to your balance above this threshold. If your TSB exceeds $10 million, you’ll have to pay an additional 10% tax on superannuation earnings attributable to your balance above this threshold. This can also reduce the incentive to contribute large amounts of cash to your super.
Why choose Ord Minnett for inheritance financial advice
Our private wealth management team has wide-ranging expertise when it comes to managing an inheritance. From navigating trusts to handling large windfalls of cash, you can rely on us for high-quality advice during this emotionally challenging time.
We use a deeply consultative process to develop strategies that are tailored for your unique needs, and we continually evolve our strategies to move with changes in your life and in the market. Above all, we’re passionate about helping you honour the legacy of your loved one by building a better financial future.
Find out why we’re trusted with $73.6 billion* in Funds Under Advice. Start a conversation with a member of our team today
Frequently Asked Questions
Do you pay tax on an inheritance in Australia?

No, Australia has no formal inheritance tax. However, taxes can apply in the process of executing an estate and managing assets. Taxes that can apply include Capital Gains Tax on inherited assets you sell, taxes up to 32% on superannuation death benefits, and stamp duty on the transfer of certain assets.
Does receiving an inheritance affect the age pension?
Yes, receiving an inheritance can directly impact your eligibility for the Centrelink Age Pension and other Centrelink payments. Almost all Centrelink payments are means-tested, and any assets you inherit must be declared to Services Australia, and could reduce or eliminate your Age Pension.
Using funds in certain ways can have a more limited impact on your ability to receive the Age Pension. For example, using funds to buy, renovate, or pay off the mortgage of a primary residence can be favourable, because your primary residence doesn’t count against the Centrelink assets test.
What is the probate process?
Probate is a legal process where the Supreme Court of the relevant state or territory validates a deceased person's will, and confirms the executor’s legal authority to manage and distribute the estate. To obtain Probate, the named executor must submit the original will, a death certificate, and a comprehensive inventory of all the deceased’s assets and liabilities.
Until Probate is granted, major financial institutions, land registries, and share registries will generally freeze accounts and block asset transfers. The probate process typically takes anywhere from a few weeks to several months. Once Probate is granted and statutory waiting periods pass, the executor can distribute cash, property, and assets to beneficiaries.
What should I do if I inherit assets from overseas?
Inheriting assets from a foreign country can become highly complex. You must first understand how local laws and regulations will impact your inheritance.Basic inheritance taxes and more complicated financial obligations may apply before you can receive your inheritance.
Australia has tax treaties and foreign tax offset agreements with many countries around the globe, designed to prevent double taxation. In some cases, foreign residents may pass on assets that have domestic tax implications, like taxable Australian property.
If you have inherited assets from another country, you should swiftly seek professional advice. Our private wealth management team is highly experienced in collaborating with legal and tax experts to provide the right advice for complicated financial situations like these.
What happens if someone dies without a will?
If someone dies without a valid will, their estate is distributed according to succession laws, which are unique to each state or territory. These laws typically prioritise spouses, partners, and children.
Since the deceased person’s estate has no designated administrator, an eligible person (usually a close relative),must apply to the Supreme Court in the relevant state or territory or Letters of Administration. This court order grants the applicant legal authority to act as the estate administrator, performing duties similar to an executor.
Should I use an inheritance to pay off my mortgage?
Paying down or clearing your mortgage is a popular option when receiving an inheritance. It can offer psychological relief, and depending on your mortgage’s interest rate, it can be an excellent way of reducing debt and long-term financial obligations. This can make it easier to reach your financial goals.
Alternatively, maintaining access to some or all of the inherited funds may provide greater flexibility while still supporting your broader financial objectives. If your debt costs are relatively low, you may decide that directing some of the inheritance towards other investments, such as a diversified share portfolio or superannuation, better aligns with your long-term goals.
The most appropriate approach will depend on your individual circumstances, financial objectives and tolerance for risk.


