

Estate planning
advice
Estate planning helps ensure your assets pass on in the ways you intend. The right estate plan helps your loved ones benefit from and continue your legacy.
At Ord Minnett, we specialise in wealth management and financial advice, giving you the ability to make informed decisions that will last lifetimes. Reach out to our private wealth management team to learn how we can help you achieve your estate management goals.

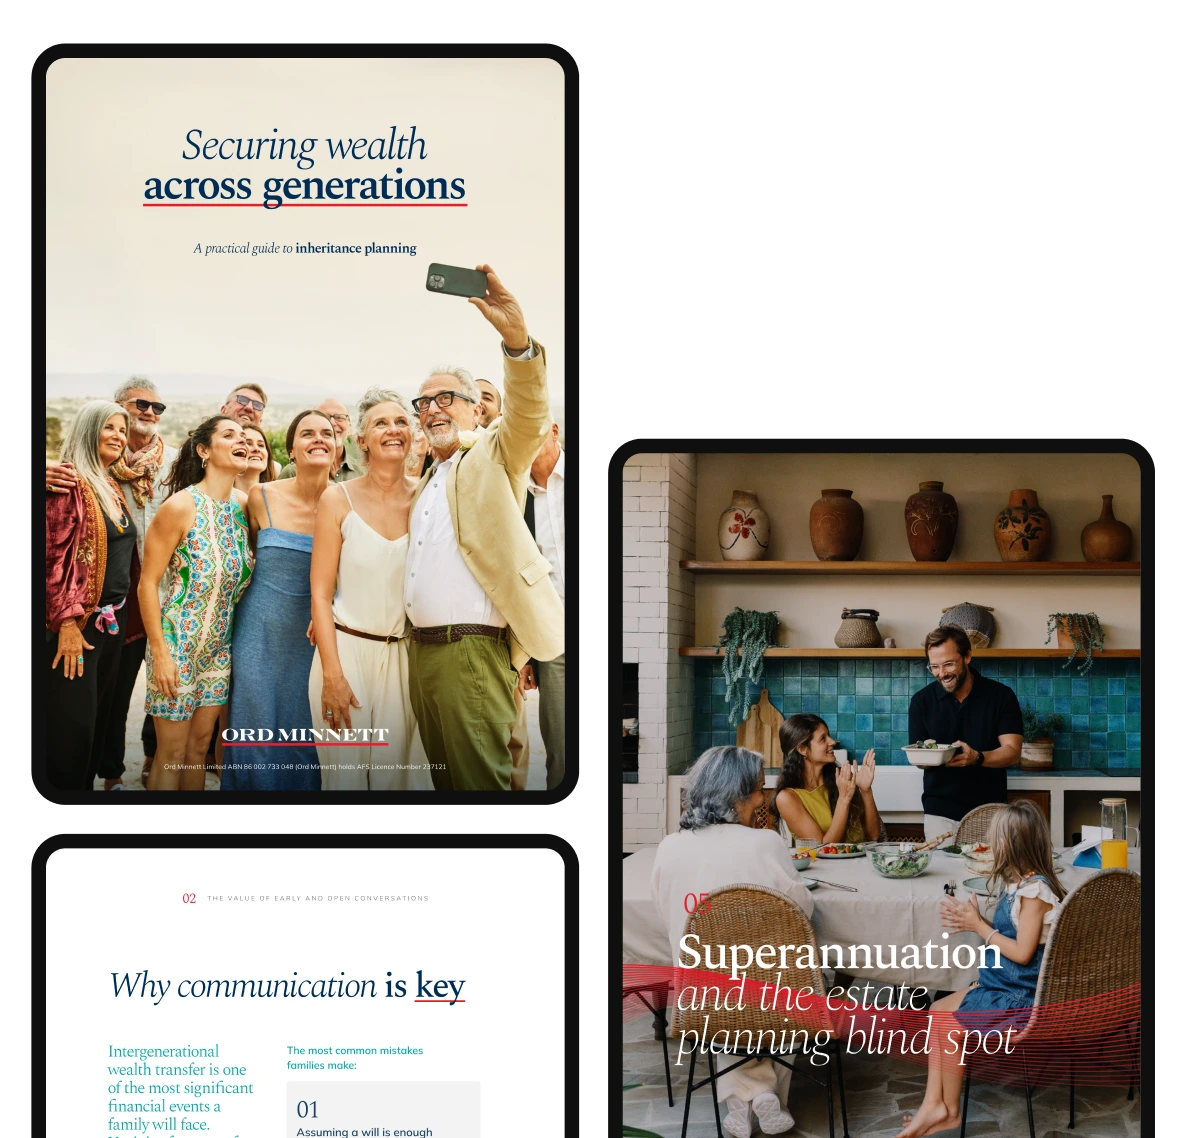
Download the inheritance planning guide
Unsure of your next move in leaving or receiving an inheritance? Download our comprehensive guide to inheritance planning.
We've broken down the key strategies to consider when you are leaving or receiving an inheritance. Get the information you need to implement an inheritance financial strategy with confidence.
We collect your personal information so we can contact you with marketing communications about our products and services. We may also use your information to improve our offerings. You can opt out of receiving marketing at any time by following the unsubscribe instructions in our communications. For more information, please see our Privacy Policy.

What is estate planning?
Estate planning involves securing the future of your assets after you pass away. There are a range of options at your disposal you can use to more efficiently pass on wealth.
When creating an estate plan, you may organise a range of documents and structures:
Will:
Your last will and testament.
Power of attorney:
To appoint a trusted person to manage financial affairs.
Enduring guardianship:
To appoint a trusted person to make your medical decisions if necessary.
Superannuation death benefit nominations:
To appoint who will receive your superannuation income.
Insurance beneficiary nominations:
Nominating who will receive your insurance payouts.
Trust and company control:
Nominating who will receive company assets.
Business succession:
Nominating who will receive ownership of a business.
How can a financial adviser help with planning your estate?
Planning your estate is an important task for the present. Here’s how working with a professional financial adviser from Ord Minnett can help you more effectively pass on your wealth to the next generation.
Will
Ord Minnett can advise you on what to include in your last will and testament. We collaborate closely with legal and tax professionals to build an integrated succession strategy, ensuring you create a valid will that can uphold your wishes.
A will that is not properly created can be contested, meaning your assets might not be passed on how you wish.
Trusts
A trust is a legal arrangement where a trustee holds and manages assets for the benefit of individuals or entities, known as beneficiaries. They can be efficient structures for passing on wealth.
A will cannot transfer assets held in a trust or owned by a company, so our private wealth management advisers can help you set up and manage your trust separately and comprehensively.
Our private wealth management team will help you understand how trusts can be best worked into your estate plan, and guide you through the process of creating them.
Superannuation
Superannuation is the single most valuable asset for many Australians. Your super is held by a fund trustee. Unless you have a Binding Death Benefit Nomination (BDBN) in place, the trustee decides who receives the benefit.
Our team will help you understand how you can most effectively pass on your superannuation. We’ll explain how factors like self-managed super funds and Division 296 can impact your plans for passing on hard-earned wealth.
Business planning
Planning for the future of your business is critical for its longevity. Making arrangements early is the key to an effective succession.
Ord Minnett works with tax and legal professionals to form concrete succession plans. We’ll help you pass on your business while creating a structure that allows it to continue to thrive.
Our estate planning approach
Our approach to estate planning is tailored to your needs and goals:
Client-first service:
We work closely with our clients and their families to determine the best estate planning approach for every circumstance.
Decision-making experts:
Ords helps you make key decisions surrounding the planning and distribution of your estate.
Unique structures:
Our team helps to develop structures like family or company trusts and SMSFs to support smoother wealth transfer.
Succession planning:
Collaborating with family members, we work with our clients to generate effective succession plans.
Collaborating with experts:
We work with and deliver estate plans to relevant parties like lawyers and tax experts for smoother asset transfer.
Estate planning for complex assets and structures
Ord Minnett understands that not every estate is simple, so we work to structure our estate planning services around even the most complex circumstances. Our team is experienced in navigating the following areas:
Family trusts:
If your wealth includes a family or discretionary trust, assets must be transferred through trust deeds, constitutions, and separate documentation. We’ll help you and your family navigate the full process of using a family trust in an estate plan.
Self-managed super funds (SMSFs):
There are over 1.24 million SMSF members in Australia now using SMSFs. Death benefit nominations and pension strategies help support you and your loved ones, but can be complex to navigate.
Business interests:
Family-owned businesses can be extremely complex to cover in estate planning. A business is not a passive asset, and requires timely settlements if ownership circumstances change. We help settle business structures in line with your interests so the process of succession is as simple as possible.
Assets held overseas:
Managing overseas assets can be difficult due to conflicting laws and procedures. We help to navigate local succession laws, tax obligations, and probate procedures.
The taxes that can apply to inherited wealth
While there isn’t a formal inheritance tax in Australia, taxes can apply in a range of scenarios when intergenerational wealth transfer takes place:
Superannuation taxes:
While certain dependants under superannuation law are excluded from death benefits tax, adults inheriting super benefits usually are not. Taxes on inherited superannuation follow the proportioning rule. The taxable component of inherited super is typically taxed at 17%, but may increase to 32%, including a 2% Medicare levy.
Stamp duty:
Also known as transfer duty, stamp duty is a tax that generally applies to some asset transfers. While stamp duty generally doesn’t apply when assets like property are inherited, it can apply in certain circumstances, such as when buying out another family member’s shares in a property.
Capital Gains Tax (CGT):
CGT can apply when you sell an asset gained from inheritance. This tax applies to profits made from business shares, investment properties, and other financial assets. You may be exempt from CGT when selling the deceased's primary residential property within two years of their passing.
Trust taxation:
As a trust isn't owned by any individual, it can be an effective method for passing on wealth. If you receive ongoing income through the trust, the value will generally be taxed as part of your income. If the legal ownership of an asset within the trust is transferred, a tax event occurs, generally adding stamp duty and CGT payments.
When to review your estate plan
Your life is always moving and changing, and so should your estate plan. Review your plan every few years for general maintenance, but keep in mind that significant life changes will require a more thorough review. Our advisers suggest reviewing your estate plan if any of the following lifestyle changes have occurred:
- Marital changes, such as a new marriage, a divorce, or a remarriage.
- Relationship changes with beneficiaries.
- Additional members have joined the family through marriage, adoption, or other means.
- The passing of a family member.
- The relocation of a beneficiary to an overseas location.
- Your business has experienced a change in ownership.
The Division 296 tax, which is in effect from 1 July 2026, may affect your superannuation. Realised super earnings attributable to the portion of a Total Superannuation Balance (TSB) between $3 million and $10 million will incur an additional 15% tax. Realised earnings attributable to the portion of a TSB over $10 million will incur an additional 25% tax. Make sure to review your estate plan if your super fund has passed either of these thresholds.
Why choose Ord Minnett for estate planning advice
When planning your estate, your personal circumstances and wishes for your assets are always at the forefront. Our private wealth management team is here to support you with your needs and goals.
We’ll help you navigate the complexities of estate planning, from family and business trusts to superannuation and the tax incurred on inherited assets. Find out why we’re trusted with $73.6 billion* in Funds Under Advice by starting a conversation with our team today.
Hear from our clients
At Ord Minnett, we've been building wealth for generations. With 270 private wealth advisers operating throughout Australia and Hong Kong, we tailor every solution to our clients' needs and goals.
[Client testimonial — not in brief, content TBC]
[Client name]
[Client testimonial — not in brief, content TBC]
[Client name]
[Client testimonial — not in brief, content TBC]
[Client name]

Building wealth for generations
As one of Australia's leading wealth advisory firms, Ord Minnett has over 270 private wealth adviser who service clients from major cities to remote communities.
270
Financial advisers focused on service excellence
15
Locations across Australia and Hong Kong
$73.6
*Billion in funds under advice as at 30 June 2026
300+
Stocks under coverage, from emerging and mid-cap to large-cap companies
154
Years of service. Ords’ corporate origins date back to 1872
Case study: Protecting everyone’s future in a blended family
How a testamentary trust brought clarity and fairness to a complex family situation
- Situation
When Graham remarried in his late 60s, he and his new wife Catherine both brought assets and children into the marriage. Graham had three adult children and Catherine had two. Graham wanted to provide for Catherine if he died first, while making sure his own children still received what he meant to leave them.
- Challenge
Without a clear plan, Graham’s estate could easily go in directions he never intended. If he left everything to Catherine, there was no guarantee his children would benefit if she remarried or died. If he split his assets as soon as he died, Catherine’s retirement security could be at risk. Either way, there was a real risk of family tension and legal disputes.
- Approach
Working with Graham’s solicitor, the adviser helped set up a testamentary trust in Graham’s updated will. The trust was designed to:
- Give Catherine a life interest in the family home, so she can live there for the rest of her life
- Ring-fence Graham’s assets so they can’t pass to Catherine’s children or a future spouse
- Make sure Graham’s three children ultimately receive their inheritance when Catherine dies or in other set circumstances
- Pay trust income tax-effectively to Graham’s children and grandchildren in the meantime
- Catherine’s own will and estate plan were reviewed (with their financial adviser and solicitor) alongside Graham’s, so both sides of the family saw the arrangement as fair and open.
- Outcome
Graham is confident that Catherine will be cared for and that his children’s inheritance is protected. Catherine knows her own estate plan looks after her children’s interests. An open family conversation about the plan eased worries on all sides and made it clear what everyone could expect.
- Key insight:
In blended families, good intentions are not enough. A testamentary trust, set up with your financial adviser and solicitor, is one of the most effective ways to protect the people you love while being fair to everyone. The best time to put one in place is well before you need it.
“Blended families are increasingly common, and so are the disputes that follow when estates are not structured properly.
A testamentary trust is not about distrust, it is about giving everyone clarity and protection.
When families have that conversation early, the outcome is almost always better for everyone involved.”
Frequently Asked Questions
What is the difference between a will and an estate plan?

A will is a legal document that confirms who you wish to receive your assets after you die. As long as your will is valid, your personal items, money, stocks, and any property are divided in accordance with it.
An estate plan is a complete strategy to distribute and protect all of your assets, working alongside your will. This plan encompasses your assets both in life and death, and includes planning for business transfers and trusts. Estate planning also encompasses powers of attorney, assigning a trusted individual to make decisions in the event you are no longer able to.
What are the components of an estate plan?
An estate plan can include the following elements:
- Your will and beneficiary designations.
- Power of attorney appointments.
- Family or company trusts.
- Superannuation Binding Death Benefit Nominations (BDBN).
- Business ownership and succession.
Do I need both a financial adviser and a solicitor for estate planning?
If you have a complex estate, multiple beneficiaries, multiple properties, investments, significant superannuation, or a business, you may benefit from working with a financial adviser in addition to a solicitor.
A solicitor can draft legally binding documents such as your will, powers of attorney and testamentary trusts. Regardless of how complex your financial situation is, you will need this input for your decisions to be legally recognised.
A financial adviser will provide the underlying strategy behind distributing your wealth, and will help you navigate the complexities of tax and insurance. Estate planning advisers will manage superannuation death benefit nominations outside of your standard will, and will evaluate tax-efficient solutions to wealth transfers.
Does my will cover my superannuation?
No, your will does not automatically cover your superannuation. Super is managed by your fund's trustee. To control who will receive your assets in the future, you must specify your wishes directly with your super fund through Binding Death Benefit Nominations (BDBN).
A financial adviser can help you to understand the role that superannuation plays in estate planning, as well as inform you of the tax consequences. Start a conversation with one of our professional advisers to learn more.
What is a testamentary trust and do I need one?
A testamentary trust is a form of trust created through your will. A major benefit of testamentary trusts is the ability to pass ongoing income onto minors without incurring the usual penalty rates.
If you’re unsure, start a conversation with a member of our team to discuss whether implementing a testamentary trust into your estate plan could be right for you.
How often should I review my estate plan?
Review your estate plan every few years, or sooner in the case of life changes. If there has been a significant change to your lifestyle, family size, relationships, or assets, a change to your estate plan may be necessary.
Will Division 296 affect my estate?
The Division 296 tax implications will affect your estate if your superannuation has exceeded $3 million in value. It imposes an extra 15% tax on realised earnings attributable to TSBs between $3 million and $10 million. An extra 25% tax applies for earnings attributable to TSBs over $10 million.
Only the earnings attributable to the portion of your TSB above the thresholds are taxed at these increased rates. For more information, see our comprehensive guide on Division 296.
What are some best practices for estate planning?
The best practices for estate planning will change depending on your assets. If you have a high number of assets such as investment properties or owned businesses, consider a financial adviser who can aid you in safeguarding your wealth for future generations.
Best practices for estate planning include:
- Having a legal, up-to-date will including beneficiary nominations.
- Nominating a power of attorney to handle certain key decisions.
- Having a list of owned assets, including properties, bank accounts, and shares.
- Updating your superannuation death benefit nominations.


